

Quick Verdict
The Orosur Mining Q1 FY2027 Earnings results show a $548,000 quarterly net loss, with continuing-operations EPS rounding to a $0.00 loss; revenue was not reported. Quarter-end cash reached $7.84 million, rising to $16.84 million following financing. Immediate stock reaction and after-hours movement were unavailable in the reviewed sources. Exploration advanced across Colombia and Argentina.
Period clarification: Although the quarter ended in calendar 2026, it is Q1 of fiscal 2027: Orosur’s preceding financial year ended May 31, 2026. The title avoids a revenue “beat” or “miss” because the statements do not report a revenue line and the reviewed sources provide no analyst consensus.
About Orosur Mining Inc.
Orosur Mining Inc. is a Canadian mineral exploration and development company incorporated in 1996. Its shares trade under OMI on both the TSX Venture Exchange and London’s AIM market. Its principal place of business is Toronto, Ontario, while its registered office is in Whitehorse, Yukon. The company’s current operations focus on Colombia and Argentina, rather than producing quarterly sales from an established mining business
Its principal assets include the Anzá gold project in Colombia and the El Pantano gold-silver project in Argentina. Orosur regained 100% ownership of Anzá in November 2024 and subsequently completed the expenditure commitments required to secure full ownership of El Pantano, subject to royalty arrangements. As of August 31, 2026, it had 401.0 million common shares outstanding. A current market capitalization was not verified, so none is estimated here. A conventional P/E comparison is not meaningful against the reported loss; the reviewed release does not provide a current dividend yield or employee count.
Top Financial Highlights
- Net income: Orosur recorded a net loss of $548,000, compared with $718,000 a year earlier—a 23.7% reduction in the loss.
- Continuing-operations result: The loss narrowed to $545,000 from $685,000.
- Operating cash flow: Cash used in operating activities declined to $381,000 from $600,000, improving by 36.5%.
- Quarter-end cash: Cash stood at $7.841 million, down from $9.954 million at May 31, 2026, but above $3.906 million a year earlier.
- Latest disclosed liquidity: Cash was $16.840 million as of the MD&A date, including proceeds from the subsequent private placement—not at quarter-end.
- Post-quarter financing: A placement closed in October raised C$16 million gross through 50 million units at C$0.32 each. Each unit included one share and half a share-purchase warrant.
- Corporate and administrative expenses: Costs increased to $462,000 from $398,000.
- Expensed exploration: Exploration and evaluation expenses rose to $178,000 from $61,000.
- Capitalized project expenditure: Additions totaled $1.573 million, comprising $1.543 million in Colombia and $30,000 in Argentina. These are investment amounts, not segment revenue; project-level revenue was not reported.
- Noncash earnings effects: A $1.001 million warrant-revaluation gain helped offset $929,000 of share-based compensation.
- Balance sheet: Total assets reached $23.835 million, total liabilities were $2.319 million, and net working capital was $6.103 million.
Orosur Mining Inc.Condensed Interim Consolidated Statements of Cash Flows
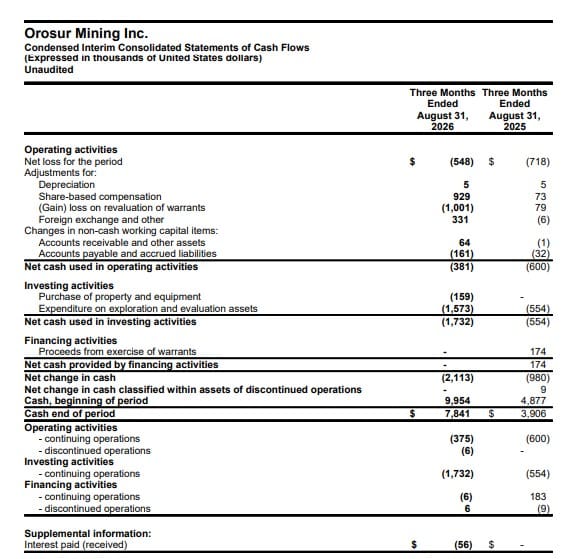
- The table presents Orosur Mining Inc.’s unaudited condensed interim consolidated statements of cash flows for the three months ended August 31, 2026, compared with the corresponding period in 2025. All amounts are expressed in thousands of United States dollars.
- Net cash used in operating activities decreased to $381 thousand in 2026 from $600 thousand in 2025, mainly reflecting changes in working capital and non-cash adjustments. Net cash used in investing activities increased to $1.732 million, compared with $554 thousand in the previous-year period, primarily due to $1.573 million in exploration and evaluation expenditures and $159 thousand in property and equipment purchases.
- Financing activities recorded no net cash inflow in 2026, compared with $174 thousand in 2025 from the exercise of warrants. Consequently, the net decrease in cash reached $2.113 million, compared with $980 thousand in 2025. Cash and cash equivalents declined from $9.954 million at the beginning of the 2026 period to $7.841 million at the end of the period, compared with a decrease from $4.877 million to $3.906 million in the corresponding 2025 period. The company also reported interest received of $56 thousand during the 2026 period.
- Overall, the statement indicates higher cash outflows in the 2026 quarter, primarily due to increased investment in exploration and evaluation activities.
Beat or Miss?
A defensible earnings beat-or-miss verdict is unavailable because no analyst consensus was identified in the reviewed reporting. The meaningful comparison is therefore against the prior-year quarter, rather than an assumed forecast.
| Metric | Reported | Difference/Analysis |
| Revenue | Not reported | Consensus: N/A; no revenue beat or miss can be established. |
| Net income/(loss) | ($548,000) | Consensus: N/A; loss narrowed by $170,000 year over year. |
| Continuing-operations EPS | $(0.00), rounded | Consensus: N/A; rounded presentation masks a small per-share loss. |
| Operating cash flow | ($381,000) | Consensus: N/A; operating cash outflow fell by $219,000 year over year. |
| Quarter-end cash | $7.841 million | Down $2.113 million from May 31, 2026. |
| Cash at MD&A date | $16.840 million | Includes post-quarter financing; not directly comparable with quarter-end operating performance. |
The central earnings-quality issue is the distinction between liquidity and profitability. The smaller net loss benefited from a noncash warrant-revaluation gain, while administrative costs, exploration expenses, and share-based compensation all increased. Meanwhile, the stronger post-quarter cash position came from issuing securities, not from operating revenue.
What Leadership Is Saying
The reviewed announcement does not contain separately attributed CEO and CFO quotations. The following are exact corporate statements, rather than comments falsely assigned to individual executives.
“The Company will focus on Colombia and Argentina whilst also looking for new opportunities in South America.”
That strategy follows drilling progress at APTA and Pepas West in Colombia, alongside the identification of a gold-silver system at Argentina’s El Pantano project. At APTA, the company reported an intersection of 135 metres grading 1.91 grams of gold per tonne, including 49 metres at 4.06 grams per tonne. These are exploration results, not evidence of established commercial production.
“The Company’s continuance as a going concern is dependent upon its ability to obtain adequate financing.”
The October placement strengthened available funding, but the financial statements retain a material going-concern uncertainty. The relevant financial question remains whether exploration spending can be supported on acceptable financing terms as the projects advance.
Historical Performance
Orosur comparison: Q1 FY2027 versus Q1 FY2026, covering the three months ended August 31, 2026 and August 31, 2025. Amounts below are US$ thousands unless stated otherwise.
| Category | Q1 FY2027 | Q1 FY2026 | Change (%) |
| Net income/(loss) | -548 | -718 | Loss narrowed 23.7% |
| Corporate and administrative expenses | 462 | 398 | 16.10% |
| Exploration and evaluation expenses | 178 | 61 | 191.80% |
| Share-based compensation | 929 | 73 | 1172.60% |
| Cash used in operating activities | 381 | 600 | −36.5% |
| Capitalized exploration and evaluation additions | 1,573 | 554 | 183.90% |
| Quarter-end cash | 7,841 | 3,906 | 100.70% |
(Source: Orosur’s interim financial statements; percentages calculated from the reported figures. Loss and cash-outflow changes compare their absolute magnitudes.)
The distinction between expensed and capitalized exploration matters. The $178,000 exploration expense affected the quarterly income statement, while $1.573 million of exploration and evaluation additions were recorded as assets. Looking only at the income-statement expense would therefore understate the quarter’s project investment and cash requirements.
Competitor Comparison
GoldMining Inc. provides a relevant exploration-sector comparison because its portfolio includes gold projects in Colombia and elsewhere in the Americas. Its fiscal numbering differs: the three months ended August 31 represent Q3, not Q1. The table uses the same calendar reporting window and retains Canadian dollars to avoid mixing currencies with Orosur’s US-dollar results.
GoldMining Inc.; amounts in C$ thousands. Prior-year figures reflect the revised comparative statements.
| Category | Q3 FY2026 | Q3 FY2025 | Change (%) |
| Consolidated net income/(loss) | -14,134 | 252 | N/M—profit turned to loss |
| Operating expenses | 14,851 | 7,598 | 95.50% |
| Exploration expenses | 11,398 | 3,764 | 202.80% |
| Net income/(loss) attributable to shareholders | -11,259 | 686 | N/M—profit turned to loss |
(Source: GoldMining’s interim statements reproduced in the October 14 regulatory disclosure. N/M means not meaningful; a conventional percentage comparison would obscure the move from profit to loss.)
GoldMining’s consolidated loss includes non-controlling interests, so it should not be confused with the smaller loss attributable to its own shareholders. This is a contextual peer comparison—not a valuation ranking—because the companies differ in project portfolios, investment holdings, and accounting exposures.
How the Market Reacted?
A verified immediate share-price reaction or after-hours movement was not available in the reviewed announcement, so no percentage move is assigned to the results. The report’s tone is cautiously constructive on exploration and funding, supported by drilling progress and the post-quarter C$16 million placement.
The counterweights are continuing operating cash outflows, increased exploration commitments, and the issuance of additional shares and warrants. Overall, the announcement is more informative about financing capacity and project progress than about an earnings-driven turnaround.

Sources