

Quick Verdict
In the latest AMD Q3 2026 Earnings report, AMD delivered adjusted EPS of $2.09 and revenue of $13.38 billion, beating Bloomberg consensus estimates as Data Center sales surged 97%. Shares gained more than 7% in after-hours trading. Fourth-quarter revenue guidance of $17 billion signals accelerating growth, although weaker gaming sales and lower operating cash flow warrant attention.
About Advanced Micro Devices, Inc.
Advanced Micro Devices, Inc. (NASDAQ: AMD) develops high-performance computing products for data centers, personal computers, gaming systems and embedded applications. Founded on May 1, 1969, by W. J. Sanders III, the company is headquartered in Santa Clara, California. Its portfolio includes EPYC server processors, Instinct AI accelerators, Ryzen PC processors and adaptive computing technologies. Barron’s lists approximately 31,000 employees, although that figure should not be interpreted as a newly disclosed quarterly headcount.
AMD’s third-quarter 2026 results show how rapidly its revenue mix is shifting toward AI infrastructure. Data Center generated $8.5 billion, substantially exceeding the combined Client and Gaming segment’s $3.7 billion. Embedded contributed another $1.1 billion. The company’s growth increasingly depends on expanding accelerator deployments and demand for server processors, while gaming remains a drag. Fbz eabxlnunt euacuac klt erd osslkp fta current market capitalization, P/E ratio, nn dividend yield; dtlz naxjadrd lcsinfoe no unsupported valuation estimate.
Top Financial Highlights
- Total revenue: $13.377 billion, up 45% year over year and 16% sequentially.
- GAAP net income: $2.428 billion, up 95% from $1.243 billion a year earlier.
- Adjusted net income: $3.471 billion, up 77% year over year.>
- Diluted EPS: $1.46 on a GAAP basis and $2.09 on an adjusted basis, increasing 95% and 74%, respectively.
- Gross margin: 54% GAAP and 56% adjusted, each improving two percentage points year over year.
- Operating income: $2.832 billion GAAP and $3.923 billion adjusted; corresponding operating margins were 21% and 29%.
- Operating cash flow: $1.202 billion, down from $2.159 billion. On a continuing-operations basis, the comparison was $1.202 billion versus $1.788 billion.
- Data Center revenue: A record $8.5 billion, up 97%, supported by EPYC processors and Instinct MI450 Series GPUs.
- Client and Gaming segment revenue: $3.7 billion, down 8%.
- Client business revenue: $2.9 billion, up 7%, driven by Ryzen mobile processor sales.
- Gaming business revenue: $773 million, down 40%, reflecting lower semi-custom and graphics revenue.
- Embedded revenue: $1.1 billion, up 29%, with growth across aerospace and defense, automotive, communications, and industrial markets.
- Cash and cash equivalents: $7.404 billion, alongside $8.372 billion in short-term investments at September 26, 2026.
- Fourth-quarter guidance: Revenue of approximately $17 billion, plus or minus 3%, implying about 66% annual growth and 27% sequential growth at the midpoint; adjusted gross margin is expected to be approximately 55%.
Advanced Micro Devices, Inc. Condensed Consolidated Statements Of Cash Flows
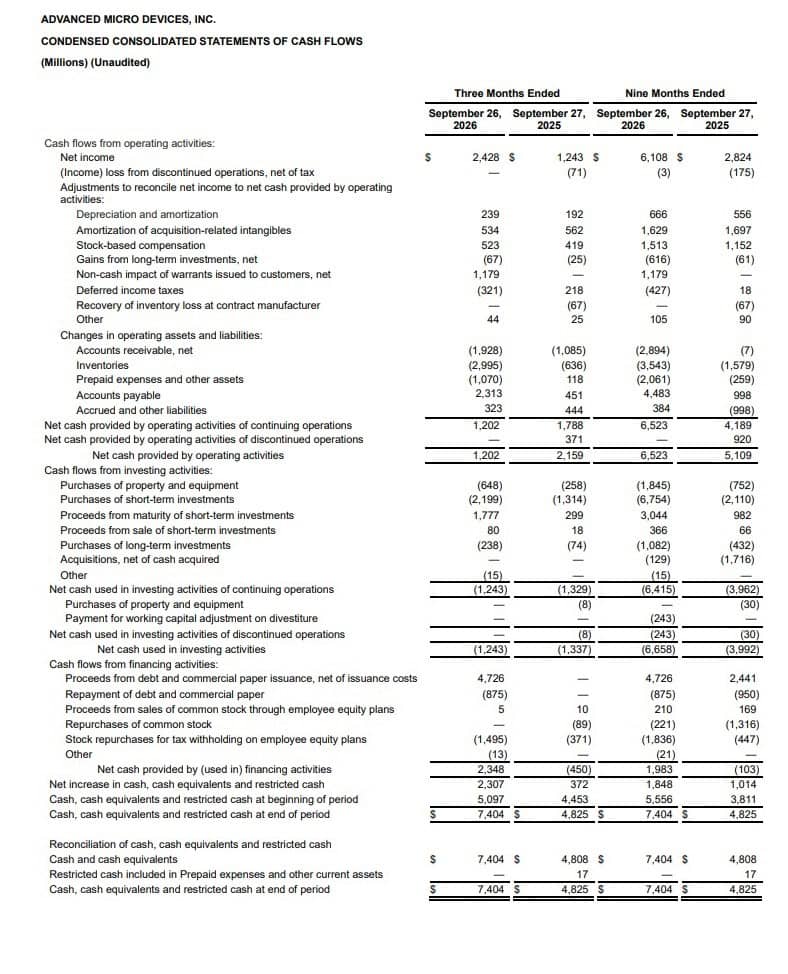
- The table presents the unaudited condensed consolidated statements of cash flows of Advanced Micro Devices, Inc. (AMD), comparing cash flow performance for the three-month and nine-month periods ended September 26, 2026, and September 27, 2025. All financial figures are reported in millions of US dollars.
- It provides a breakdown of cash flows from operating, investing, and financing activities, including net income, depreciation and amortization, stock-based compensation, changes in operating assets and liabilities, capital expenditures, investment purchases, debt repayments, and stock repurchases.
- During the nine months ended September 26, 2026, AMD reported net income of $6,108 million, compared with $2,824 million in the corresponding period of 2025. Net cash generated from operating activities increased to $6,523 million from $5,109 million. Net cash used in investing activities reached $6,658 million, compared with $3,992 million, while net cash generated from financing activities stood at $1,983 million, compared with a net cash outflow of $103 million in 2025.
- Consequently, the company’s net increase in cash, cash equivalents, and restricted cash reached $1,848 million, compared with $1,014 million in the previous year. Cash, cash equivalents, and restricted cash at the end of the period totaled $7,404 million, compared with $4,825 million in 2025.
- The table highlights AMD’s improved profitability, stronger operating cash generation, and increased cash position during the reported period, alongside higher investment-related cash outflows.
Beat or Miss?
AMD posted a beat on both revenue and adjusted EPS. The comparisons below consistently use Bloomberg consensus figures reported by Yahoo Finance; estimates from other providers differ, so mixing them would produce inconsistent surprise calculations.
| Metric | Reported | Difference/Analysis |
| Total revenue | $13.377 billion | Versus $13.08 billion expected; approximately $297 million, or 2.3%, above consensus. |
| Adjusted diluted EPS | $2.09 | Versus $1.97 expected; a $0.12, or approximately 6.1%, beat. |
| GAAP diluted EPS | $1.46 | Comparable GAAP consensus: N/A in the retrieved coverage. |
| Data Center revenue | Approximately $8.5 billion | Versus $8.19 billion expected; approximately $310 million above consensus, using rounded reported revenue. |
| Client revenue | Approximately $2.9 billion | Versus $3.06 billion expected; approximately $160 million below consensus. |
| Gaming revenue | $773 million | Versus $655 million expected; $118 million above consensus despite the annual decline. |
The beat was not uniform across the business: Data Center outperformed, while Client missed expectations. Separately, AMD’s $17 billion fourth-quarter revenue outlook exceeded the $16.2 billion LSEG consensus cited by CNBC, but its 55% adjusted gross-margin outlook was slightly below StreetAccount’s 55.3% estimate. These outlook benchmarks come from different providers than the quarterly comparisons above.
What Leadership Is Saying
Lisa Su, AMD chair and CEO, linked the company’s outlook to rising demand and production expansion:
“Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production.”
Jean Hu, executive vice president, CFO and treasurer, emphasized earnings growth and operating leverage:
“Third quarter revenue grew 45% year-over-year to a record $13.4 billion, while non-GAAP earnings per share grew 74%, demonstrating the significant operating leverage in our business model as our Data Center business drives scale.”
Together, the comments frame AMD’s strategy around scaling AI and server products while growing earnings faster than revenue. The financial results support that operating-leverage argument, although cash generation did not follow the same upward trajectory during the quarter.
Historical Performance
AMD’s fiscal third quarter ended September 26, 2026; the comparable prior-year quarter ended September 27, 2025. Dollar amounts below are in millions, except EPS. Percentage changes follow AMD’s rounded reported comparisons.
| Category | Q3 2026 | Q3 2025 | Change (%) |
| Revenue | $13,377 | $9,246 | 45% |
| GAAP net income | $2,428 | $1,243 | 95% |
| GAAP operating expenses | $4,378 | $3,510 | 25% |
| GAAP operating income | $2,832 | $1,270 | 123% |
| Adjusted net income | $3,471 | $1,965 | 77% |
| Adjusted diluted EPS | $2.09 | $1.20 | 74% |
Revenue grew considerably faster than operating expenses, lifting GAAP operating margin from 14% to 21%. However, operating cash flow fell as working-capital needs increased: inventory absorbed $2.995 billion, and receivables absorbed $1.928 billion during the quarter, partially offset by higher accounts payable. This separates strong accounting earnings growth from weaker near-term cash conversion.
Competitor comparison: Intel
Intel provides a same-quarter comparison, having reported Q3 2026 results on October 29. Its reporting periods ended on the same dates as AMD’s. Dollar amounts are in millions; changes below are calculated from Intel’s disclosed figures and rounded to one decimal place.
| Category | Q3 2026 | Q3 2025 | Change (%) |
| Intel revenue | $16,513 | $13,653 | 20.90% |
| Intel consolidated net income | $3,520 | $4,270 | −17.6% |
| Intel operating expenses | $4,574 | $4,535 | 0.90% |
| Intel operating income | $2,522 | $683 | 269.30% |
| Intel net income attributable to Intel | $3,320 | $4,063 | −18.3% |
AMD’s revenue growth outpaced Intel’s, while both companies reported substantial operating-income improvement. Intel’s lower net income despite higher operating income illustrates why bottom-line comparisons require attention to non-operating items: Intel reported interest and other income of $1.130 billion, down from $3.670 billion a year earlier.
Nvidia is also a relevant competitor, but its next earnings release was scheduled for mid-November. Its fiscal-quarter labels should not be treated as interchangeable with AMD’s calendar-year Q3, so an unreported or mismatched Nvidia quarter is not inserted into this table.
How the Market Reacted?
AMD shares closed November 3 at $483.90, up 3.65%, before rising to $518.70 in a delayed after-hours quote timestamped 5:10:09 p.m. EST—a further 7.19% gain. Other reports captured different points in extended trading: CNBC reported an approximately 6% jump, while Barron’s later cited a 7.9% rise to $521.94. The positive reaction accompanied the revenue and earnings beats and stronger fourth-quarter sales outlook, although gaming weakness, lower operating cash flow and the sequential decline implied by adjusted gross-margin guidance remain important counterweights.
Additional recent coverage is available through Yahoo Finance’s November 3 earnings report, Barron’s after-hours update, and CNBC’s earnings-versus-expectations analysis; the linked citations provide access to those sources. Market prices above are timestamped observations, not a verified final extended-session close.