

Quick Verdict
The Children’s Place Q2 2026 Earnings showed a GAAP Q2 2026 loss of $1.39 per share and an adjusted loss of $0.82 per share, while revenue fell to $241.8 million. Both adjusted EPS and sales missed consensus expectations. PLCE shares reacted sharply negatively, falling about 22.9% in the September 15 trading session.
About The Children’s Place
The Children’s Place, Inc. (Nasdaq: PLCE) is a U.S.-based specialty retailer focused on value-priced children’s apparel, footwear, accessories, and related products. Founded in 1969, the company is headquartered in Secaucus, New Jersey. Its principal proprietary brands are The Children’s Place and Gymboree, marketed through an omni-channel model spanning company-operated stores, digital storefronts, wholesale marketplaces, and international franchise and wholesale partners.
At the end of the second quarter of fiscal 2026, The Children’s Place operated 514 North American stores, up from 494 a year earlier, and maintained distribution across 13 countries through 10 international franchise and wholesale partners. The company’s market capitalization was approximately $52.5 million in the immediate post-results period, reflecting the steep share-price decline. Because PLCE reported trailing losses, a meaningful price-to-earnings ratio is not available; the company also did not report a dividend yield in the earnings release.
Top Financial Highlights
- Net sales declined 18.9% year over year to $241.8 million, from $298.0 million in Q2 2025.
- GAAP net loss widened to $31.0 million, compared with a $5.4 million net loss in the prior-year quarter.
- GAAP diluted loss per share was $1.39, versus a loss of $0.24 per share a year earlier.
- Adjusted net loss was $18.2 million, or $0.82 per diluted share, versus an adjusted loss of $3.4 million, or $0.15 per share, in Q2 2025.
- Direct-to-consumer sales fell 15.0%, primarily because of lower traffic; comparable retail sales in the owned-and-operated DTC business decreased 16.7%.
- Wholesale revenue was also pressured by a planned reduction in shipments intended to align inventory with customer needs and liquidate aged fashion inventory.
- Gross profit decreased to $83.3 million, from $101.3 million in the prior-year period.
- Reported gross margin rose 40 basis points to 34.4%, aided by $39.0 million in tariff refunds recorded as a reduction in cost of sales.
- Excluding the tariff refunds, gross margin declined 1,550 basis points, reflecting elevated markdowns, tariffs, store occupancy costs from new openings, and inventory reserves.
- SG&A expenses increased slightly to $90.1 million from $89.6 million, but rose to 37.2% of net sales from 30.1% because the lower sales base reduced expense leverage.
- Operating performance swung to a $13.0 million operating loss, from $4.1 million of operating income in Q2 2025.
- Net interest expense more than doubled to $18.3 million, from $8.0 million, largely because of financing-cost amortization related to monetized tariff-refund and income-tax-receivable claims.
- Cash and cash equivalents were $7.2 million as of August 1, 2026; total liquidity, including revolving-facility capacity and Mithaq commitment availability, was $79.7 million.
- Inventory declined 23.2% to $340.2 million, a reduction of $102.5 million year over year.
- The company opened 19 stores and closed two during Q2, ending the period with 514 stores.
Beat or Miss?
The company missed the reported analyst consensus measures available in contemporaneous market coverage. Its adjusted EPS loss was worse than expected, while revenue came in below consensus by roughly $10.3 million.
| Metric | Reported | Difference/Analysis |
| Adjusted EPS | ($0.82) | Missed consensus loss estimate of $(0.62) by $0.20 per share. |
| Revenue | $241.8 million | Below consensus estimate of $252.09 million by approximately $10.29 million, or about 4.1%. |
| GAAP EPS | ($1.39) | No directly comparable GAAP consensus figure was identified in the sourced market coverage. |
| GAAP net loss | $(31.0 million) | Loss widened substantially from $(5.4 million) in Q2 2025. |
| Gross margin | 34.40% | Reported margin rose 40 bps, but the increase depended on $39.0 million of tariff refunds; excluding them, margin fell 1,550 bps. |
| Q3 / FY2026 guidance | Not provided | Management discussed improving August traffic and a holiday wholesale inventory rebuild but gave no numerical outlook. |
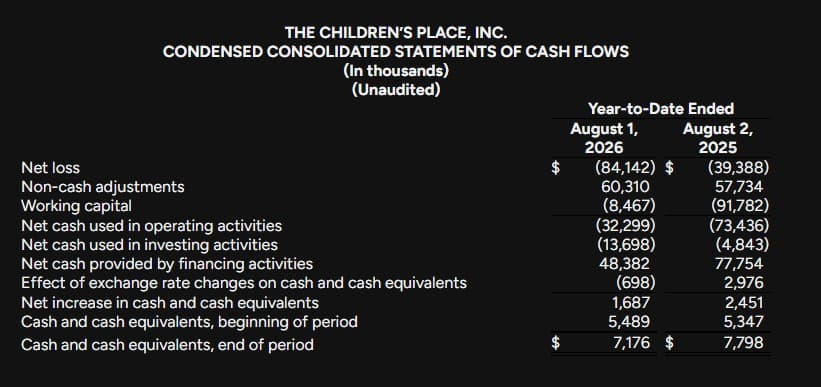
The Children’s Place, Inc. Condensed Consolidated Statements Of Cash Flows
(Source: quiverquant.com)
- The table presents The Children’s Place, Inc. condensed consolidated statements of cash flows for the year-to-date periods ended August 1, 2026 and August 2, 2025, with figures reported in USD thousands.
- The company reported a net loss of USD 84.1 million in 2026, compared with a net loss of USD 39.4 million in 2025. Despite the larger loss, operating cash flow improved considerably. Net cash used in operating activities decreased to USD 32.3 million from USD 73.4 million in the previous year. This improvement was supported by USD 60.3 million in non-cash adjustments and a much smaller USD 8.5 million negative working-capital impact, compared with USD 91.8 million in 2025.
- Cash used in investing activities increased to USD 13.7 million in 2026, compared with USD 4.8 million in 2025. Meanwhile, financing activities provided USD 48.4 million in cash, lower than the USD 77.8 million provided in the prior-year period.
- Foreign exchange movements had a negative impact of approximately USD 0.7 million in 2026, compared with a positive impact of USD 3.0 million in 2025. Overall, cash and cash equivalents increased by USD 1.7 million during the 2026 period, compared with an increase of USD 2.5 million a year earlier. Ending cash and cash equivalents stood at USD 7.2 million, slightly below USD 7.8 million in 2025.
- Overall, the table indicates that although the company recorded a substantially larger net loss in 2026, its operating cash outflow improved significantly, while lower financing inflows and higher investing outflows limited the increase in its cash balance.
What Leadership Is Saying
The company did not identify a separately titled chief financial officer quote in the September 14 release. The available executive commentary came from President and Interim Chief Executive Officer Muhammad Asif Seemab; the second quote below addresses liquidity, costs, and the operating model rather than attributing remarks to a CFO.
“Despite the near-term headwinds, we continue to invest in the long-term strength of the business focused on our strategic priorities: improving our customer experience, strengthening and elevating the brand, delivering on financial targets and enhancing organization leadership.” — Muhammad Asif Seemab, President and Interim Chief Executive Officer
“While we continue to execute our transformation plan and remain focused on cost reduction in all aspects of the business to optimize efficiencies, we are also evaluating our operating model to function in a profitable manner and improve our immediate liquidity position.” — Muhammad Asif Seemab, President and Interim Chief Executive Officer.
Historical Performance
| Category | Q2 2026 | Q2 2025 | Change (%) |
| Revenue / net sales | $241.8 million | $298.0 million | -18.90% |
| Net income (loss) | $(31.0 million) | $(5.4 million) | Loss increased by approximately 477.0% |
| Operating income (loss) | $(13.0 million) | $4.1 million income | Declined by $17.1 million; moved from profit to loss |
| Gross profit | $83.3 million | $101.3 million | -17.80% |
| SG&A expense | $90.1 million | $89.6 million | 0.50% |
| Gross margin | 34.40% | 34.00% | +40 bps, aided by tariff refunds |
| Inventory | $340.2 million | $442.7 million | -23.20% |
| Store count | 514 | 494 | 4.00% |
Competitor Comparison
A like-for-like Q2 2026 competitor comparison cannot be completed from The Children’s Place release alone because it provides no current-quarter financial results for named rivals. The closest direct peer is Carter’s, another major North American children’s apparel retailer, but a valid comparison requires Carter’s most recent reported quarter, which may use a different fiscal calendar and reporting period.
| Category | The Children’s Place Q2 2026 | Competitor Data | Change / Analysis |
| Revenue | $241.8 million | N/A in the PLCE release | PLCE revenue declined 18.9% YoY. |
| Net income (loss) | $(31.0 million) | N/A in the PLCE release | PLCE’s net loss widened from $(5.4 million) in Q2 2025. |
| Operating expenses / SG&A | $90.1 million | N/A in the PLCE release | SG&A increased 0.5%, but deleveraged substantially as sales fell. |
How the Market Reacted?
Investor reaction was strongly negative after the earnings release. PLCE shares fell approximately 10.9% immediately following the announcement in one market report, while StockTitan’s session tracking showed a 22.87% decline in the September 15 trading session, with trading volume at 8.9x the daily average.
The sell-off reflected the combination of an adjusted EPS miss, a revenue shortfall, sharply lower DTC sales, a wider GAAP loss, and concern that reported margin expansion was driven by a one-time $39 million tariff-refund benefit rather than improved underlying profitability.